Registration and verification
Alawin registration and KYC are linked processes rather than two unrelated steps. Registration creates the account record; verification can later test whether the identity, age, residence, source of funds and payment methods connected to that record are genuine. Current Alawin Terms allow KYC checks before or after deposits and in connection with withdrawals. They also state that requested information can include certified identification, proof of residence, evidence of payment-method ownership and transaction histories, and that additional security checks such as phone or face verification may be used.
The current Terms say requested documents and information must be supplied within 30 days of the request. Once a request has been answered in full, Alawin says it will usually verify the material within 10 days, while allowing extra time or additional checks for more complex cases. That is not a guaranteed approval time. The most useful preparation is therefore to keep registration data accurate, use payment methods in your own name and respond to the exact request rather than guessing what the operator wants.
Registration creates the identity record that KYC later checks
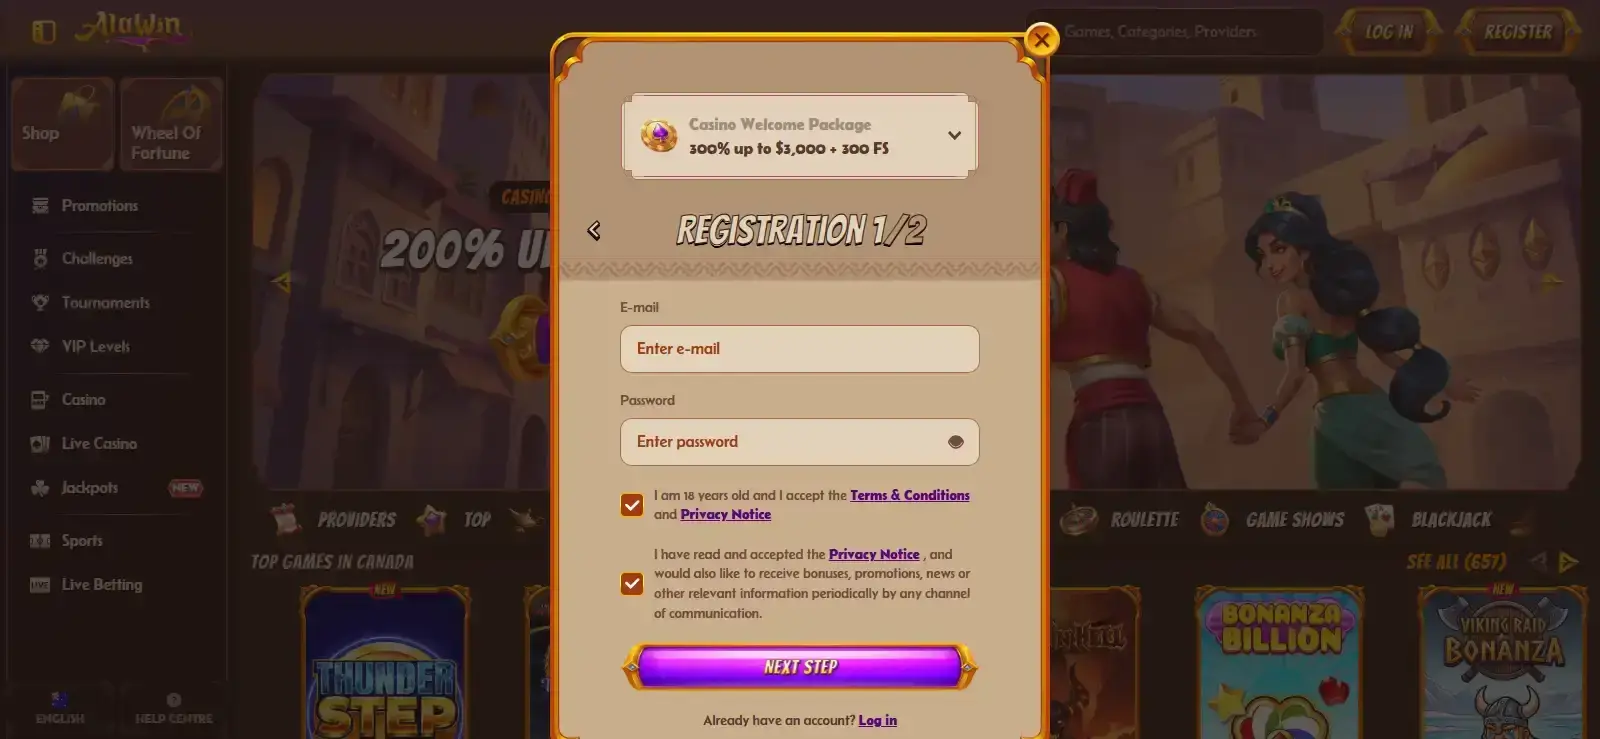
Alawin’s Terms require an account to be registered in the user’s own correct name and say the information provided in the registration form must be true and complete. They also require account details to be kept up to date. These rules matter because KYC does not begin from a blank slate: the operator compares later evidence with the information already attached to the account.
The current privacy notice says registration data may include email address, date of birth, country, phone number, gender, full name, social security number, postcode and username depending on how a person interacts with the service, while IP address and location data can be received during registration. The live registration form is still the place to check which fields are actually required in your session.
If a detail changes after registration, update it through the available account or support process instead of creating a second account. The Terms restrict duplicate accounts and permit account closure or sanctions when duplicate-account rules are breached. The broader Alawin account guide explains how registration, payment activity and withdrawal fit together across the full account lifecycle.
What Alawin can request during KYC
The current Terms explicitly say the operator can request information needed to manage the account, verify identity or establish the source of funds deposited to the account. Examples in the Terms include properly certified identification, proof of residence, proof of ownership of the payment methods used and transaction histories such as bank or credit/debit card statements. The privacy notice separately lists due-diligence data such as identity-card, driving-licence or passport information, proof of address, source-of-wealth or source-of-funds information, bank ID and financial details.
This is an authority to request evidence, not a universal checklist that every account holder receives. The exact request can depend on the account history, the payment method, the amount and pattern of activity, and any risk signals the operator’s checks identify. A user might be asked for a subset of the items described in the Terms, or for additional verification where the operator considers it necessary.
That distinction is important when preparing documents. Do not assume that uploading every document you possess will speed up the review. Read the request, match each requested category to the clearest current evidence, and keep the submitted material consistent with the account record.
Identity and age checks
Identity and age are core verification targets under the Terms. The operator can use additional procedures it considers appropriate to verify identity, age, residence and other circumstances, including checks before and after deposits and during withdrawals. It can also use third-party identity-verification or fraud-prevention services and may carry out security checks by phone or face verification.
For an Australian user, the practical implication is that the name and date-of-birth details entered at sign-up should match the identity evidence you would provide later. If your legal name has changed or the account data contains a genuine error, resolve that discrepancy through support rather than trying to make the evidence fit an incorrect profile.
The Terms do not promise that one specific identity document will always be sufficient. They provide examples and reserve the right to conduct further checks. The document types listed in the Terms are therefore examples of possible evidence rather than a fixed one-size-fits-all submission pack.
Residence evidence and address consistency
Proof of residence is another item specifically contemplated by Alawin’s Terms. The purpose is not only to show a person’s name but also to establish where the account holder resides and whether that information matches the account. The refund section of the Terms gives examples of proof-of-address material such as a utility bill, bank statement or rental agreement, but the verification team can determine what it will accept for a specific case.
Use a current document that clearly connects the account holder to the address when that is what the request asks for. Cropped images, incomplete statements or documents where the name or address is obscured can create another question. If you have recently moved, make sure the profile is updated before relying on a new address document.
Residence checks should also be separated from questions of regulatory authorization. An Australia-facing site and an Australian address field do not by themselves prove that the operator holds an Australian online-casino licence. The Australia regulation guide deals with that separate issue.
Source-of-funds checks are broader than ordinary identity verification
Source-of-funds review asks a different question from “who are you?” It concerns where the money used on the account came from and whether the financial activity can be explained. Alawin’s Terms specifically allow requests to verify the source of funds deposited to the account and allow withdrawal processing to be delayed while source-of-funds checks are carried out.
The operator’s privacy notice also describes collection of source-of-wealth or source-of-funds information and financial details for due-diligence purposes. The exact evidence needed can vary. Depending on the request, a user may need to show transaction history or another financial record that connects the funds to the account holder.
The practical approach is to answer the specific question asked and preserve the transaction trail. If deposits come from multiple methods, keep records that show ownership and the movement of funds. If a request is ambiguous, ask support what period, account or transaction they need documented before submitting unrelated financial information.
Payment-method ownership can become part of KYC
Alawin’s Terms state that the credit/debit card or other payment method used to top up the account must belong to the account holder. They also say proof of ownership and transaction history for payment methods can be requested during verification. In the refund provisions, the Terms again say payment-method ownership verification may be required.
This is one reason to avoid deposits from another person’s card, bank account or wallet. Even if a transaction is technically accepted, later ownership checks can create a mismatch between the account holder and the source of payment. Use the Alawin withdrawals for the separate payout rules and timing; here the key point is that payment ownership forms part of the identity trail.
Wherever possible, keep the same core personal details across the casino account and the payment method. A different formatting of an address is not necessarily a problem, but a different person as the account holder is materially different and can trigger a more serious review.
When verification can be triggered
The Terms allow checks both before and after deposits and before a withdrawal is completed. That means there is no single guaranteed trigger. Verification may occur during routine account use, when a user submits a payout, after a payment-method change, or when additional security or anti-fraud review is considered necessary.
A withdrawal is a common point of attention because the operator can delay processing while checking identity, account balance, source of funds and compliance with the Terms. The Terms also reserve the right to postpone payment until required verification procedures have been completed. This is why waiting until the day of a large withdrawal to think about KYC can create avoidable pressure.
Prepare by keeping account details current, retaining accessible transaction records and watching the account inbox or registered email for requests. If the operator asks a follow-up question, treat that as a continuation of the same case rather than assuming the original upload automatically completed the review.
The current 30-day response requirement and 10-day usual review period
Alawin’s present Terms contain two timing points that should not be confused. First, the user must provide requested documents and information within 30 days after the request is made. Second, the operator says it will usually verify the documents and information within 10 days after its request has been answered in full. The Terms expressly allow additional time or checks where the circumstances or complexity require them.
The phrase “answered in full” matters. If the verification team asks for three items and only two are supplied, the usual review period described by the Terms does not necessarily begin from the first upload. Likewise, a follow-up request can extend the practical timeline even when the first response was prompt.
Record the date and contents of each request and response. If a case appears inactive after a complete submission, contact support with the chronology rather than starting a new ticket that omits the earlier context. The timing language is a current official benchmark, not a guarantee that approval or payment will occur by a fixed calendar date.
How to prepare a cleaner verification submission
- Read the request literally. Identify whether it asks for identity, residence, payment ownership, transaction history or source-of-funds evidence.
- Check account consistency. Make sure the name, date of birth and address on the profile are accurate before submitting documents.
- Use clear, current files. Avoid cropped images that remove the information needed to connect the evidence to you.
- Keep payment ownership obvious. Where a card, bank account or wallet is involved, retain records that identify the account holder and relevant transaction.
- Preserve the chronology. Save the request date, upload date and any follow-up messages.
- Ask before guessing. If the wording is unclear, use live chat or the support email listed in the Terms to ask exactly what evidence is needed.
This process does not guarantee approval, but it reduces the chance that the review stalls because the submission fails to answer the actual request.
What KYC does not prove
Passing identity verification does not itself establish that a casino is locally licensed in Australia, nor does it guarantee future withdrawals, bonus eligibility or uninterrupted account access. KYC is an account-control process. Licensing, promotion rules and payment conditions are separate questions with their own evidence.
It is also incorrect to assume that an account which has already passed one verification step can never be checked again. Alawin’s Terms permit additional checks and allow the operator to investigate identity, activity and source-of-funds issues later. A change in payment method or activity can therefore create a new verification question.
Keeping these boundaries clear helps avoid overinterpreting a successful KYC outcome. Verification confirms whatever the completed checks establish at that time; it is not a blanket guarantee about every other aspect of the service.
Preparing for Alawin verification before a withdrawal request
The practical way to approach Alawin KYC is to make the account easy to verify from the start. Register with accurate personal information, use payment methods you own, keep address details current and retain a readable record of deposits and payment ownership. If Alawin asks for identity, residence, source-of-funds or other evidence, respond to the exact request and keep a copy of what was submitted.
Current official Terms provide a 30-day deadline for supplying requested material and describe a usual 10-day verification period after a request has been answered in full, while allowing additional time or checks. Treat those figures as current process terms rather than a promised approval date. If a first withdrawal is your next step, confirm that verification is complete and then use the dedicated withdrawal guidance to check the payout rules that apply separately.
For related context, see trust and licensing.