Account lifecycle guide
An Alawin account is the point where registration, identity checks, payments and device access meet. For an Australian user, the practical sequence is to register with accurate personal details, keep those details current, expect KYC checks before or after deposits and withdrawals, and treat mobile access as browser-based unless a genuine app-store listing is independently confirmed. Current Alawin Terms allow checks of identity, age, residence, source of funds and ownership or history of payment methods. They also say only one account is permitted per person, household or address, phone number or email, and IP address.
The account should therefore be planned around the full lifecycle rather than the sign-up form alone. A registration that takes only a few minutes can still lead to later verification work before a withdrawal is released. Alawin currently offers live chat on its Australia-facing site and lists [email protected] in its Terms, which gives users two routes for account questions. The account lifecycle runs from sign-up through possible verification and the first withdrawal; the dedicated registration and KYC covers verification in more depth.
The account lifecycle: registration is only the first step
It is useful to think of an Alawin account as five connected stages: registration, first login, funding, verification and withdrawal. Each stage can affect the next. Registration data identifies the account holder. Payment details create an ownership trail. KYC checks can compare those details against identity and residence evidence. A withdrawal can then be delayed if required checks have not been completed or if the operator needs more information about the account, balance or source of funds.
This sequence matters because the lowest-friction approach is to avoid contradictions from the start. Use your own name, your own contact details and payment methods that belong to you. Keep the country, address and other personal details accurate. Alawin’s current Terms state that the account must be registered in the user’s own correct name and that registration information must remain up to date. They also state that payment methods used to fund the account must belong to the account holder.
Do not assume that creating the account guarantees continued access. The Terms reserve the right to deny opening an account or close an existing account. That is different from normal KYC review: registration can succeed technically while the account is still subject to later checks. In practical terms, the account is not fully “finished” simply because the dashboard becomes available.
What the current registration route shows
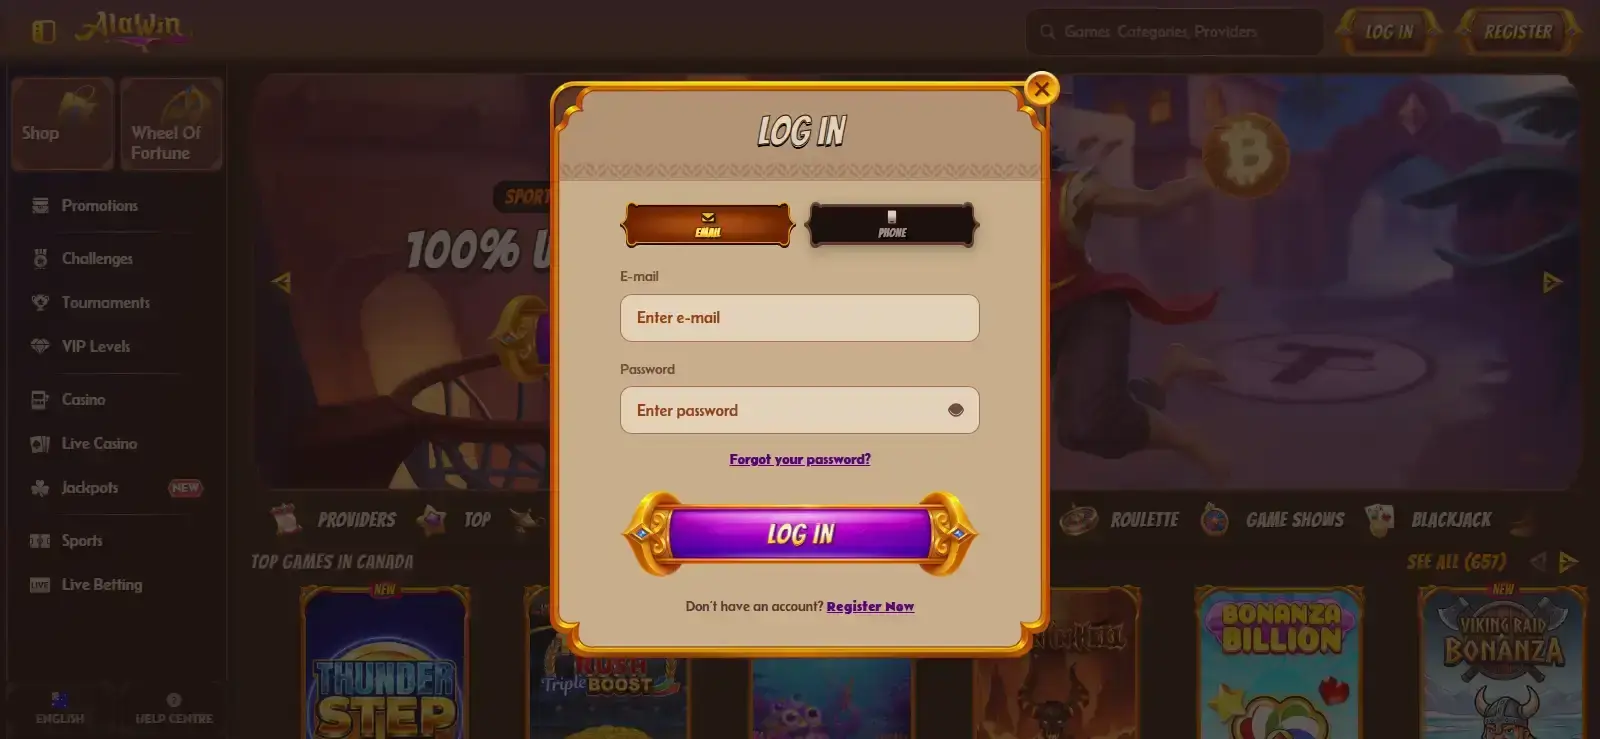
The current Alawin registration flow presents a registration route from the Australia-facing site and a welcome-bonus choice before account creation. The public registration page also repeats the 18+ requirement. The exact fields shown can change, and the operator’s privacy notice lists a broad set of registration data that may be collected depending on the interaction, including email address, date of birth, country, phone number, gender, full name, postcode and username, with IP and location data received during registration.
The safest way to treat that list is as a description of data the service may collect, not a promise that every field appears in every Australian registration form in the same order. Before submitting, review the live form and make sure the entered details match the documents you would be able to use later if verification is requested. Small inconsistencies can create avoidable back-and-forth when the account is reviewed.
Where the live form offers a bonus choice, decide separately whether the promotion is actually useful. Bonus selection can add wagering rules and other conditions to the account. The bonuses section explains those trade-offs; this account page is concerned with identity, access and continuity rather than bonus value.
Why KYC should be expected before a first withdrawal
Alawin’s current Terms give the operator broad authority to verify identity, age, residence and other circumstances, both before and after deposits and in connection with withdrawals. They can also request information about the source of funds deposited to the account. The Terms specifically mention properly certified identification, proof of residence, proof of payment-method ownership and transaction histories such as bank or card statements as examples of information that may be requested.
The wording is important: this is not a fixed checklist that every user receives. The Terms say the requests can include those items and that additional procedures may be used. The operator also reserves the right to carry out calls, face verification or other security checks when needed. That is why an Australian user should prepare for verification without assuming a single universal document bundle.
For a more detailed walkthrough of likely triggers, evidence types and payment-ownership checks, use the Alawin registration and KYC page. The key point at account level is simpler: if you intend to withdraw, keep identification, address information and payment ownership consistent with the profile from the beginning.
Current verification timing: useful benchmark, not an approval promise
The official Terms currently state that requested documents and information must be supplied within 30 days after the request is made. They also say Alawin will usually verify the material within 10 days after the request has been answered in full, while warning that additional time or checks may be required depending on the circumstances and complexity of the case.
That timing is best treated as an operator-side review benchmark. It does not guarantee that a specific account will be approved within 10 days, and it does not mean a withdrawal will reach a bank or wallet within the same period. If the request is incomplete, the clock described in the Terms is not the same as a completed response. A practical record should therefore note when the operator asked for information, when the final requested item was supplied, and whether further questions followed.
If the verification request is unclear, use live chat or the support email listed in the Terms before uploading unrelated material. Sending more documents than requested can complicate the record without necessarily answering the actual check.
From deposit to first withdrawal
The payment stage connects account setup to verification. Alawin’s Terms say deposits and withdrawals use payment systems available on the website from time to time and that withdrawals are processed through the same method used to fund the account wherever possible. They also allow verification of payment-method ownership. This makes the first deposit method more than a convenience choice.
Before depositing, confirm that the method is in your name and that you can access the records needed to prove ownership if asked. Avoid moving money through another person’s card, wallet or account. Keep transaction confirmations. If your method changes later, retain enough information to explain the relationship between the old and new funding routes.
When you reach the first payout, read the withdrawals before submitting. The current Terms include an internal withdrawal-processing window and AUD limits by account level, but a payout can still be held while verification checks are completed. Preparing the account early does not remove KYC; it reduces preventable inconsistencies when the checks occur.
Mobile access: separate browser compatibility from app claims
Alawin’s public Australia-facing site is accessible through a web interface that can be used on modern mobile browsers. That is enough to discuss mobile web access, but it is not evidence of a native iOS or Android application. A casino can have a mobile-optimised website, a home-screen shortcut or installable web experience without having a verified listing in Apple’s App Store or Google Play.
No native Alawin app should be assumed without a current official app-store listing. If you want to use Alawin on a phone, start with the browser version and check whether the site’s own interface offers a shortcut feature. The dedicated Alawin mobile separates mobile web behaviour, shortcut options and any future native-app evidence.
Security matters more on a shared or portable device. Use a unique password, avoid leaving the account signed in on a shared browser, and do not share login credentials. Alawin’s Terms make the account holder responsible for keeping the login and password confidential and treat activity performed with the correct credentials as account activity.
Support routes and what to record before contacting them
The Australia-facing site currently displays Live Chat, and the Terms list [email protected]. Those are the two verified support routes relevant to routine account issues. Before contacting support, prepare the account username or email, the approximate time of the issue and a concise description of what changed. For a payment or KYC question, include the transaction or request context without exposing passwords or unnecessary sensitive data in an open chat.
For verification, it is useful to ask what exact item is missing rather than asking a broad question such as “why is my account blocked?” For withdrawals, distinguish between a pending request, a request under verification and a payment already marked processed. Each state points to a different next step.
If you need to close the account, the current Terms say closure can be requested through customer support by email, subject to account-balance and pending-withdrawal conditions. Responsible-gambling support should be treated separately from ordinary technical troubleshooting.
Common account mistakes that create avoidable friction
- Using inconsistent identity details: a nickname, shortened name or outdated address can later conflict with verification evidence.
- Funding with someone else’s payment method: Alawin’s Terms require ownership of the payment method used to top up the account.
- Opening another account after a login problem: the Terms restrict duplicate accounts across several identifiers, so support is the safer route.
- Assuming KYC only happens at withdrawal: the Terms allow checks before or after deposits and around withdrawals.
- Treating a mobile website as proof of a native app: browser access and app-store availability are different facts.
- Waiting until a payout to organise records: keeping payment and account records from the start can make later requests easier to answer.
None of these steps guarantees approval or a particular processing outcome. They simply keep the account history coherent, which makes it easier to respond accurately if Alawin exercises the verification rights set out in its Terms.
Planning an Alawin account from registration to first withdrawal
For an Australian user, the practical account plan is to register with accurate information, use payment methods in your own name, keep the profile current and expect KYC to be part of the normal account lifecycle. Alawin’s present Terms allow identity, residence, source-of-funds and payment-ownership checks and currently describe a usual verification period after a request has been answered in full, while allowing extra time for more complex cases.
Use the browser experience without assuming that a native app exists, and keep the verified support routes available in case registration, verification or withdrawal status becomes unclear. Most importantly, treat the first withdrawal as the point where earlier account choices are tested: consistent identity data, traceable payment ownership and complete responses to verification requests matter more than how quickly the original sign-up form was completed.
For related context, see main Alawin Australia page.